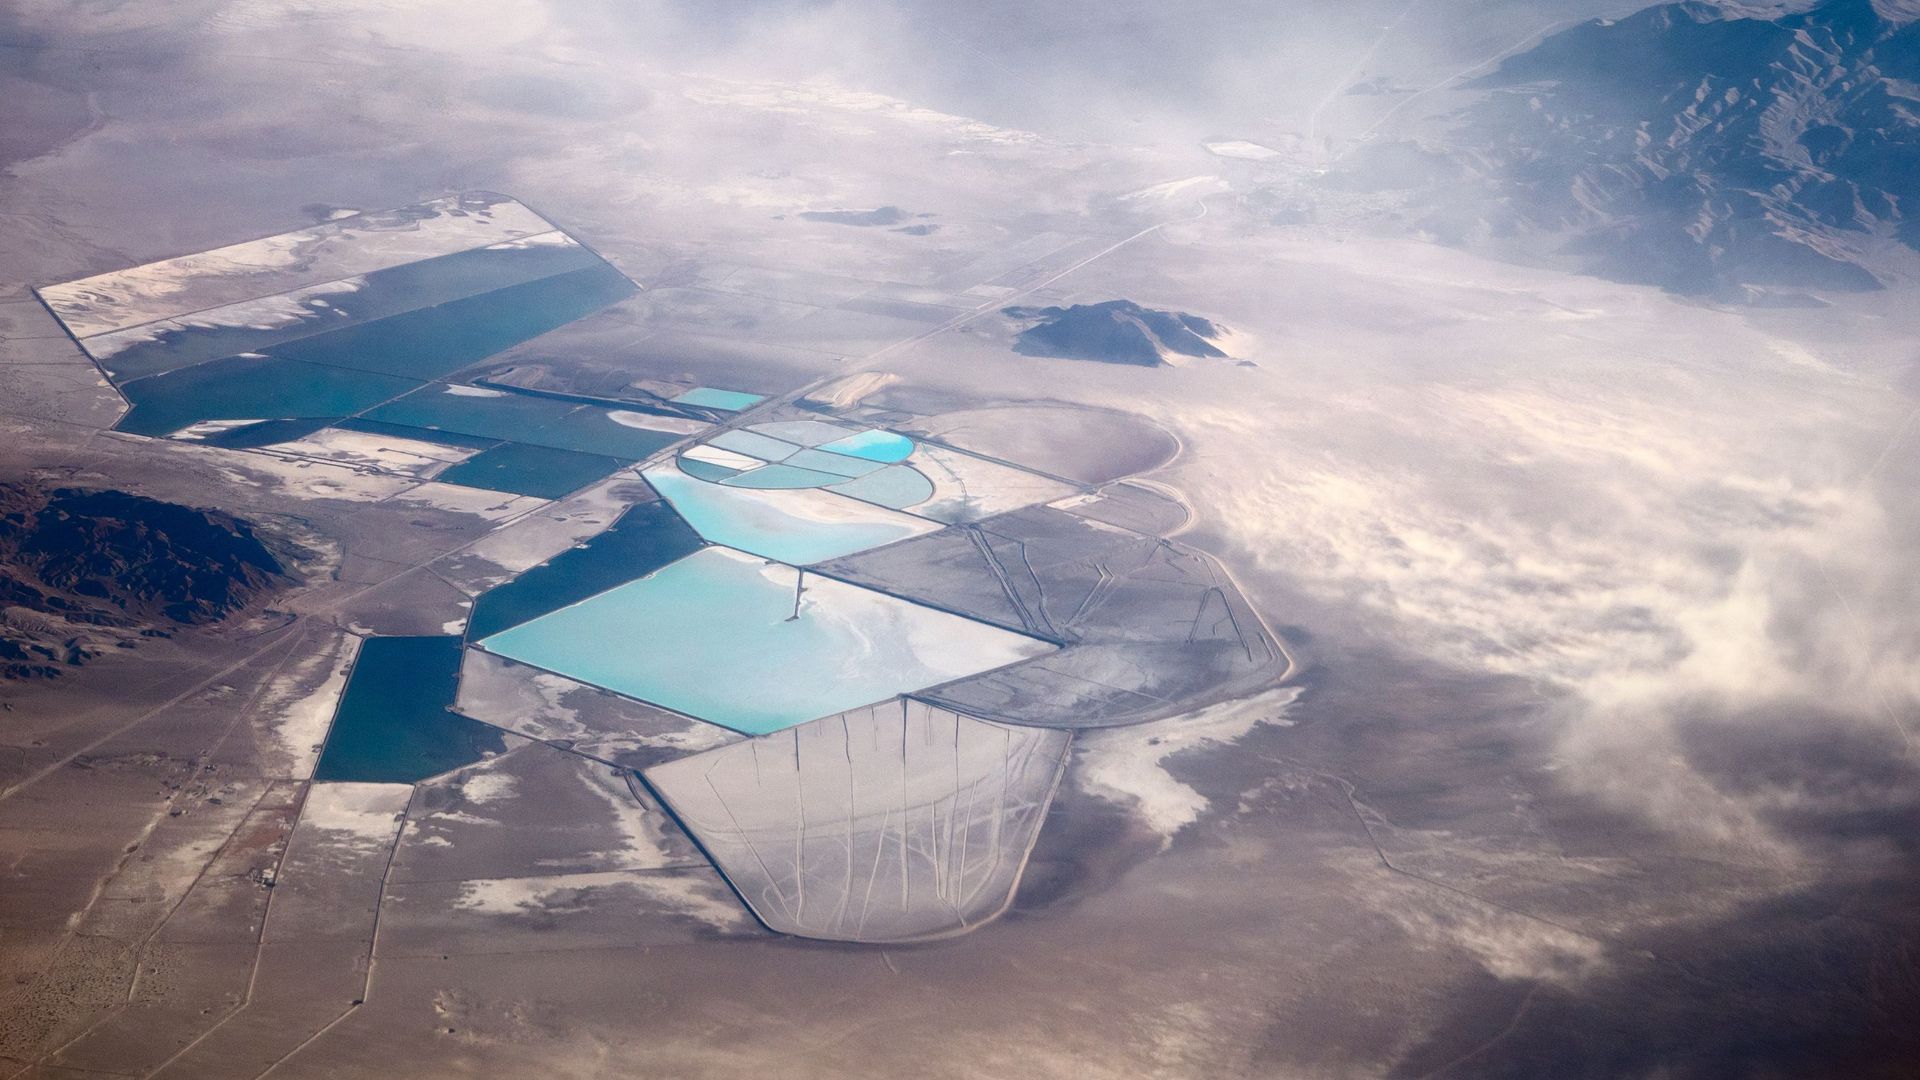
In December 2025, Chile launched NovaAndino Litio, the world’s largest brine-lithium producer, placing the Salar de Atacama, the country’s largest salt flat, under state-anchored control through 2060. This new period in Chile’s lithium management is an important opportunity, since Chile has built a durable, state-led lithium strategy and is ready to work with international partners on the terms it has set. The National Lithium Strategy (ENL) sets a plan to manage the world’s largest lithium reserves. Chile is now the second-largest producer of the metal that is key for electric vehicles, grid storage, and modern electronics.
Some voices in the international debate treat state-led resource producers as a risk for foreign investors. But foreign economies, including the United States, should see Chile’s model as compatible with their interests, as its strategy is open to foreign investors as long as they collaborate with its national development goals.
A Governed, Stable Model
The ENL is a structured public-private strategy that is predictable and transparent. Under NovaAndino, Chile’s copper firm (Codelco) holds a 50% plus one share, giving the state operational control of the Salar de Atacama from 2031. Chile keeps 70% of the venture’s operating margin through 2030, rising to 85% thereafter, with the government projecting roughly $6 billion a year for the treasury. After clearing more than 20 national and international regulatory approvals and its final domestic legal review in early 2026, the framework moved into implementation with long-term certainty supported by contracts that run to 2060.
The ENL has two pillars: accumulating rents and an explicit bet on domestic technology and value addition. The strategy created the National Institute of Lithium and Salt Flats (INLiSa) to develop new brine-extraction methods, novel battery applications, and materials recovery, and it preserves the Chilean Economic Development Agency’s preferential, below-market lithium pricing for companies that manufacture cathodes and batteries inside Chile.
The flagship Salar Futuro project (filing for environmental approval in 2026) is built around new, lower-water extraction technology rather than evaporation ponds. In late 2025, INLiSa opened an international call for technology developers to validate their solutions on real Chilean brine as it designs a national lithium-technology piloting platform.
These agendas reflect Chile’s active pursuit of partners for joint technological innovation projects, marking a shift from the old strategy of seeking mere investors for mineral extraction.
What the United States Can Bring
The ENL’s technology-focused design matches capabilities the United States is well positioned to offer. U.S. public financing for critical-minerals projects has expanded sharply through initiatives like the $10 billion Project Vault reserve, the U.S. Export-Import Bank’s (EXIM) $14.8 billion in letters of interest, and a Development Finance Corporation (DFC) now authorized to invest in countries like Chile.
Indeed, Chile is already a leading supplier of processed lithium to the U.S. market. U.S. firms, meanwhile, are major players in the direct-lithium-extraction and refining technology the ENL is adopting; one U.S. geothermal-brine lithium project alone drew a $1.4 billion federal commitment. That expertise maps directly onto INLiSa’s open invitation and Chile’s brine-based Salar Futuro, providing a ready-made basis for joint pilots, shared research, and co-investment in value-added production.
Policy Recommendations
The U.S. Congress should:
- Fund value addition, not just extraction. Direct EXIM and the DFC (and structure Project Vault offtake) to co-invest in ENL-aligned refining, cathode, and battery-materials projects and joint research in Chile. Financing downstream capacity, not only raw-material supply, builds a deeper and more resilient partnership.
- Keep allied partners fundable. Preserve the DFC’s expanded authority to invest in high-income allies, so ENL-aligned projects that include local processing and technology transfer remain eligible.
The U.S. administration, including the Departments of State, Trade, and Energy, should:
- Plug into the platform Chile already built. Connect U.S. national laboratories and extraction-technology firms to INLiSa’s piloting platform and open call for technologies, cooperation that Chile has explicitly invited.
- Support U.S. participation in Chile’s value-addition program. Encourage U.S. manufacturers to take up the Chilean Economic Development Agency’s preferential-pricing offers for cathode and battery-materials production inside Chile.
Lastly, the government of Chile should:
- Use the strategy’s leverage to attract technology partners. Provide clear and stable rules to bring in international technology partners and require technology transfer, so the ENL’s developmental goals are advanced and sustained through the political transition.
Conclusion
Chile’s National Lithium Strategy turned a passive exporter into a governed, state-anchored player that controls its salt flats, captures its rents, and plans to build its own technology. It is a stable, transparent framework — one that has openly invited international partners to help develop it. INLiSa’s international call, the bilateral consultations, and Salar Futuro’s 2026 permitting are all live right now. The United States, with its financing tools and technological strengths, is well placed to become a lasting partner in Chile’s lithium future. Washington should take up that invitation, on the terms Chile has set, and build a partnership that endures. Particularly in a scenario of intense geopolitical competition for strategic minerals, developing countries have more leverage to negotiate better contracts. If the United States wants privileged access to critical minerals, it should prepare to offer deals that are better than its competitors.