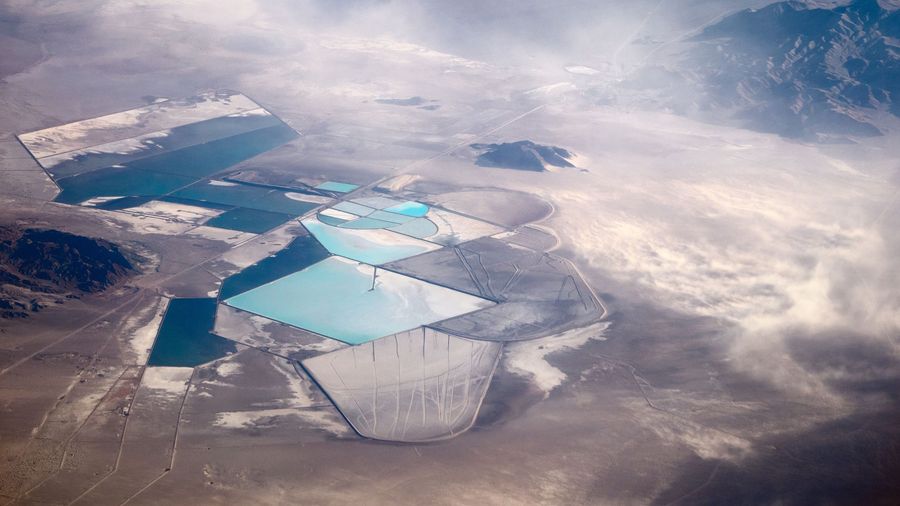
Chile’s future as a lithium powerhouse currently sits in a permitting queue. The South American nation holds the world's largest lithium reserves, yet it lost the production lead to Australia a decade ago. Now it faces a decisive test. The joint venture between Codelco, Chile’s state-mining company, and SQM, a major Chilean mining and chemical company, has entered environmental review for a multibillion-dollar project, called Salar Futuro, which would govern the Atacama salt flat through 2060. Its timeline depends less on capital than on water science, permits, and the consent of Indigenous communities that the last round of negotiations divided.
Here is where U.S. supply strategy meets Chile’s lithium reality. The Trump administration has mobilized billions of dollars in financing commitments for critical minerals and signed minerals frameworks with a dozen partners, including Chile in March. Congress has also expanded the Development Finance Corporation's mandate so countries such as Chile are now eligible for its investment.
Thus, the capital and the mandates are in place. What is not in place yet is a shared understanding of why Chilean lithium moves slowly. It is not because the state now owns too much of it, but because six decades of extraction never built the water science, local industry, or community trust that a 30-year contract requires.
The Challenges Facing Chile’s Lithium Sector
Chile’s structural lithium problem. The Atacama salt flat holds the overwhelming majority of Chile's lithium reserves and a substantial share of the world’s, yet the country ships out lithium chemicals and imports back the batteries. The production is an enclave, with high margins, few local linkages, and heavy water use in a desert where Lickanantay communities have farmed for millennia. Chile’s own critical minerals strategy identifies moving up the value chain as a national priority precisely because the current model captures so little of it.
The National Lithium Strategy changed who captures the value, but not what Chile makes. Launched in 2023, it required majority state participation in new projects. The result is a joint venture formed at the end of 2025 in which the state holds just over half the equity and takes a large and rising share of the operating margin on new production through taxes, development agency payments, and Codelco’s profits.
That is a serious fiscal gain. But the product mix is unchanged, downstream processing remains marginal, and the strategy’s institutional core — made up of a national lithium company, a protected salt flat network, and a research institute — has arrived late and incomplete.
Consent without cohesion. Dozens of Atacameño communities and associations, along with municipalities and the regional government, stand to receive substantial annual payments under the agreement, and the venture formalized a governance model with most of them. Yet the process left the Atacameño people divided: communities closest to the wells demanded compensation for damage, more distant ones demanded equal shares, and the consultation records document accusations that some Atacameño communities created artificial groups solely to collect benefits.
In early 2024, southern communities blockaded access to the salt flat to win a seat at the table. Legal analysts have questioned whether the consultations met international human rights standards.
Deregulation can only defer this institutional and social risk. President José Antonio Kast’s government merged the economy and mining portfolios under a single minister and has signaled faster permitting and lighter regulatory and tax burdens. Investors have welcomed the tone, but Chile’s recent delays have stemmed from institutional failure, not excessive consultation. In fact, the comptroller general rejected special operating contracts awarded under the previous administration for procedural defects. Meanwhile, a separate Atacama proposal that cut brine and water extraction cleared regional review without incident this year.
The pattern is not that Chilean permitting is slow, but that projects the territory supports move, and projects it distrusts stall. Approvals granted over community objection end up in court, face protests, or land in the next government’s review file. This unpredictability is a problem for potential U.S. investors.
Policy Recommendations
In the current international context, host countries are seeking not just more foreign direct investment, but also greater installed productive capacity and social legitimacy. Chile is no exception, and the U.S. government can help its investors advance shared-prosperity agendas with Chilean counterparts — making U.S. capital both highly competitive and a credible partner in the lithium sector.
For the U.S. Congress. Current mandates steer Export-Import Bank of the United States and Development Finance Corporation financing toward upstream projects whose output ships to the United States. Congress should broaden that authority to cover midstream processing built in partner countries. Diversification that stops at the mine leaves the refining bottleneck exactly where it is, and financing that reaches only extraction reproduces the structure Washington says it wants to change.
For the Chilean government. Keep the community agreements and the state-majority structure as the regime’s stable core, and make publishing salt flat water-balance data a permanent obligation. The speed gained by shortening the consultation window will be lost in litigation.
Conclusion
Washington’s interest in Chile is a long-term partnership. That depends on decisions being made in the Atacama right now, in an environmental review whose hardest test is trust. The United States can become a key strategic partner on the terms that build trust — like open science, financed processing, and verified community benefit — or it can enter the lithium sector through speed alone and inherit the instability that speed produces. Only one of those is durable.